Welcome to Lender Lens, our series for profiling leaders in the Lender community.
With private credit playing an increasingly important role in the financial system, we wanted to find out how lenders are navigating the evolving landscape and how they assess the market in the coming years.
Dealmaking has become more complex in today’s market — and private credit is adapting.
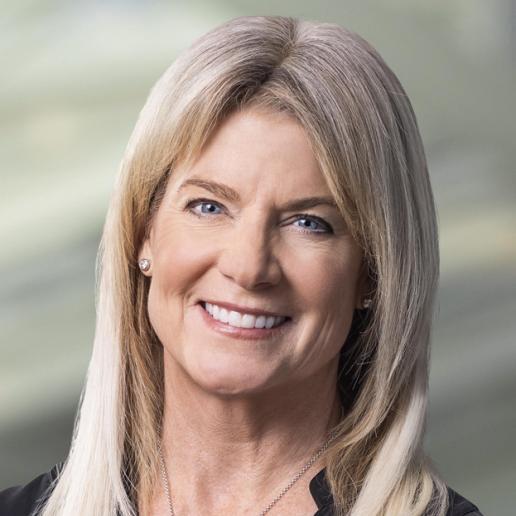
In this edition of Lender Lens, we speak with Dianna Carr-Coletta, Managing Director, Middle-Market Direct Lending at PGIM Credit, about the value of long-term relationships and investment discipline in an increasingly competitive private credit market.
Drawing on more than three decades of experience across origination, corporate finance and workouts, Dianna shares how PGIM’s insurance heritage shapes its approach to underwriting, why non-sponsored lending is often misunderstood and what managing distressed investments has taught her about assessing risk.
She also reflects on the evolution of private credit, the importance of mentorship and the leadership lessons that have influenced her career.
PGIM was built inside an insurance company and invests both permanent insurance capital and third-party client capital. How does that shape the way you think about underwriting, borrower relationships and investing through cycles?
Insurance companies have provided capital to companies through private transactions for more than 150 years, and PGIM has been investing in private credit for over 75 years.
That insurance company heritage shapes how we approach the market. We focus on credit fundamentals, cash flow, downside protection and preserving capital through cycles. Those principles aren’t unique to private credit today. These are principles insurance companies have relied on for generations to ensure strong balance sheets to meet their liabilities such as life insurance and annuities.
It also means that we can bring a long-term perspective to our borrower relationships. Most of our capital is from insurance companies and the long-term nature of the liabilities backing that capital informs how we work with borrowers. It means that we can focus on establishing long-term relationships based on partnership and provide certainty of execution when our borrowers need capital solutions.
At the end of the day, we’re not just underwriting transactions. We’re helping businesses in the real economy achieve their strategic goals and grow over the long term.
Before your current role, you led PGIM’s Corporate and Project Workout team, managing the restructuring of non-performing investments. How has that experience shaped the way you underwrite new ones?
Leading the workouts team gave me a unique perspective on the critical issues businesses face when conditions become more difficult. When you’re originating a deal, it’s easy to focus on the growth story. When a company is in financial stress or in a workout situation, you’re focused on cash flow, liquidity, capital intensity and whether the company can navigate a tougher market environment and ultimately weather a storm.
Having that background in workouts has helped inform a focus on credit fundamentals. Does the business have a reason to exist? Can it generate cash flow? Can it support the capital structure through a cycle? Those are the things that matter most when market conditions change, and they continue to inform how I think about underwriting today.
Walk us through what origination actually looks like for a non-sponsored deal. How does a company end up in front of PGIM in the first place?
Our origination network is one of the things that really differentiates PGIM. We have more than 40 regional origination teams operating from 17 offices globally. The model actually resembles a commercial bank more than a traditional direct lender because our origination teams spend years building relationships with companies in their local markets, often before there’s any financing need at all. Our teams are divided into geographical focus areas, and a big part of their job is to simply get to know every medium-sized private company in that area. When I worked in originations covering Wisconsin, I put over 200,000 miles on my car simply driving around the state, meeting with owners, CEOs and CFOs of local companies.
In many cases, we first meet a company when it’s founder- or family-owned and still relatively small. We get to know the management team, understand the business and build a relationship long before a transaction occurs. Then, when the company needs capital for an acquisition, recapitalization, expansion project or other strategic initiative, we’re positioned to help.
As ownership structures change, financing needs and business complexity evolve, we can often continue supporting that company along the way and through its stages of growth. That’s the real power of the platform and a result of the origination network.
What do you find people misunderstand most about non-sponsored direct lending?
A common misconception is that non-sponsored lending is inherently riskier. In our experience, many non-sponsored borrowers exhibit characteristics such as lower leverage and stronger lender protections. These are often family- or founder-owned businesses, and management teams generally are not looking for the last dollar of leverage. They’re borrowing to achieve a strategic objective, whether that’s growth, an acquisition or shareholder liquidity. That typically results in a lower leverage profile and lender protections more reflective of what you find in the bank market. These stronger protections are an absolutely critical part of the process and a product of the way that we source deals through durable relationships.
How do you think about pricing and terms in a market with this much capital competing for deals?
Pricing and terms are important, but so are the factors supporting them. We spend just as much time thinking about cash flow, leverage, covenants, documentation and downside protection as we do pricing.
In competitive markets, it’s easy to focus on winning deals, but we’re lenders first. We’d rather maintain discipline and be patient than stretch on risk.
In private credit, success doesn’t come from making the most loans. It comes from preserving capital, managing through cycles and consistently seeking attractive risk-adjusted returns for investors.
You’ve been at PGIM for over two decades, across origination, corporate finance and workouts. What has and hasn’t changed about how PGIM approaches credit since you started in this business?
Private credit has grown and matured significantly. When I joined, it was largely viewed as an extension of commercial banking and insurance investing. Today, it’s a mainstream asset class with a much broader set of participants and strategies. You’re also seeing increased interest from the wealth and retail channels as investors look for income-producing assets that can provide diversification and access to parts of the private markets that have traditionally been available only to institutional investors.
This is still a relationship-driven business. Borrowers want partners who understand their businesses, can provide certainty through different market environments and can support them as their needs evolve. Trust is still earned over time, and experience still matters when markets become challenging.
You work with Girls Who Invest to bring more women into investment management. What’s your pitch to a young woman considering the industry today?
My advice would be to stay curious, ask questions and not be intimidated if you don’t see people exactly like you in the room. Your perspective is valuable.
What has kept me in this industry for more than 30 years is that every day is different. You’re constantly learning, meeting interesting people and helping businesses. As an Advisory Board Member of Girls Who Invest, I’ve seen how powerful it can be when someone realizes there’s a place for them in this industry and has a mentor who helps them navigate it. That’s just one of the reasons I’m passionate about the organization. Sometimes all it takes is helping someone see that they belong and can build a successful career doing work they genuinely enjoy.
You’ve been recognized for your leadership in the industry. Who’s had the biggest influence on the way you lead?
Upon reflection, my leadership style has grown out of watching three very different individuals, all of whom worked at PGIM. Each person had a significant impact on my view of how leadership looks.
The first would be Julia Buthman. She taught me how to drive business tenaciously. She would refer to herself as the human equivalent of a Jack Russell terrier. She also taught me the importance of mentorship, guiding me as I built my career while balancing family demands.
The second would be Scott von Fisher. Scott was an amazing manager and treated all of his employees like family. He created an environment where people could thrive by working hard while also having fun. If you enjoy what you do, you do it better.
Finally, I would say Allen Weaver. Allen was the ultimate leader in his ability to set strategic direction, keep everyone focused on what matters and, as he would say, remind us that “the score takes care of itself.” He was also adept at running interference when needed, so his team could stay focused on driving business success. While he often asked for other opinions and took them into consideration, he also took control and made decisions when necessary. If one of those decisions turned out to be the wrong one, he acknowledged it and pivoted appropriately.
Over the years, I’ve tried to incorporate each of these traits into my own leadership style.
If you’re interested in sharing your perspective and being featured in our Lender Lens series, please fill out the form and we’ll be in touch.